TailCurve Basics#
import chainladder as cl
import pandas as pd
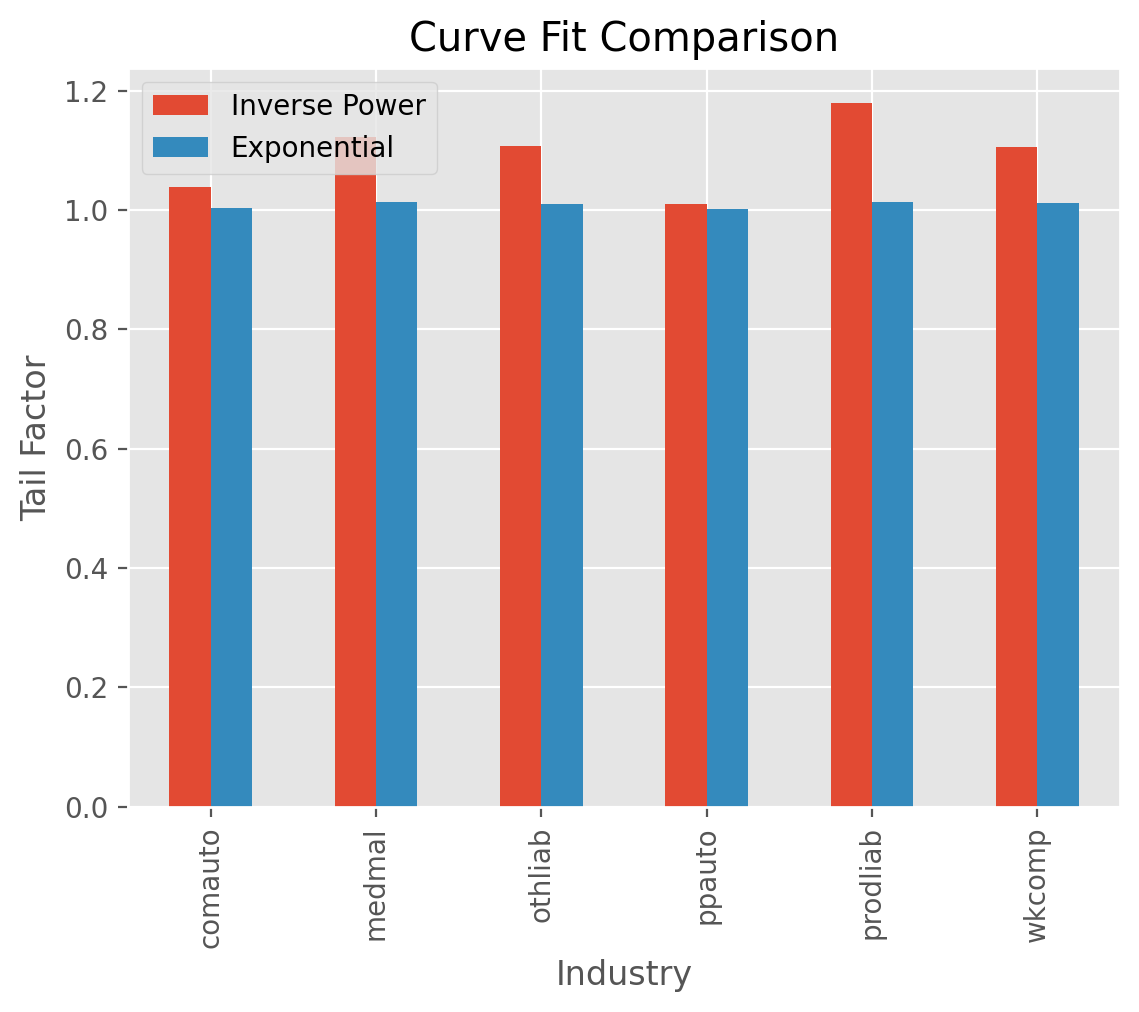
This example demonstrates how the inverse_power curve generally produces more
conservative tail factors than the exponential fit.
clrd = cl.load_sample("clrd").groupby("LOB").sum()["CumPaidLoss"]
cdf_ip = cl.TailCurve(curve="inverse_power").fit(clrd)
cdf_xp = cl.TailCurve(curve="exponential").fit(clrd)

result = pd.concat(
    (cdf_ip.tail_.rename("Inverse Power"), cdf_xp.tail_.rename("Exponential")), axis=1
)